Irrespective of your profession, what comes to your mind when you first hear about a cashless transaction? Visualize that you have purchased groceries and vegetables from the local shop, and the bill amount has come to Rs.1847.80. You have multiple options today to pay without physical cash because digital payments have become convenient, faster, safer, and traceable.
The Reserve Bank of India had launched Central Bank Digital Currency (CBDC) in November 2022, taking a significant step toward the digitalisation of money and the future of payments.
Central banks, which represent nearly 98% of global GDP, are now exploring central bank digital currencies, and India stands at the forefront of this revolution. But what exactly is the digital rupee? How is it different from the UPI payment you just pictured? And can it succeed in a country where digital payments are already thriving?
What Is a CBDC and How Does India’s e-Rupee Actually Work?
E-Rupee, India’s Central Bank Digital Currency, is a digital representation of the country’s physical currency. Issued by the Reserve Bank of India, it offers the convenience of digital transactions while retaining the reliability and government backing of cash.
We use UPI to make digital payments, and transactions occur between banks, but a CBDC is itself an actual currency. There is a designated app developed by several banks under the Reserve Bank of India, where customers have to link their accounts and transfer funds to the app. Balance is deducted from the account, and we can see the digital currency in the app. The RBI directly controls every Digital Rupee in circulation.
The implication of CBDC for financial transactions, policy, and the structure of the financial system will depend on how the CBDC is designed. In India, the Digital Rupee operates through both retail and wholesale models, serving the needs of consumers as well as financial institutions. Beyond simply digitising money, the design of a CBDC could enable programmable payments, allowing funds to be used only for specific purposes or under predefined conditions.

India’s e-Rupee: From a 334% Surge to a 2026 Reality Check
The Reserve Bank of India first launched it on a pilot basis in large cities, with detailed guidelines. Wholesale CBDC launched in November 2022, and Retail in December 2022. Initially, this pilot covered only selective cities under the Closed User Group (CUG), which includes participating customers and merchants.
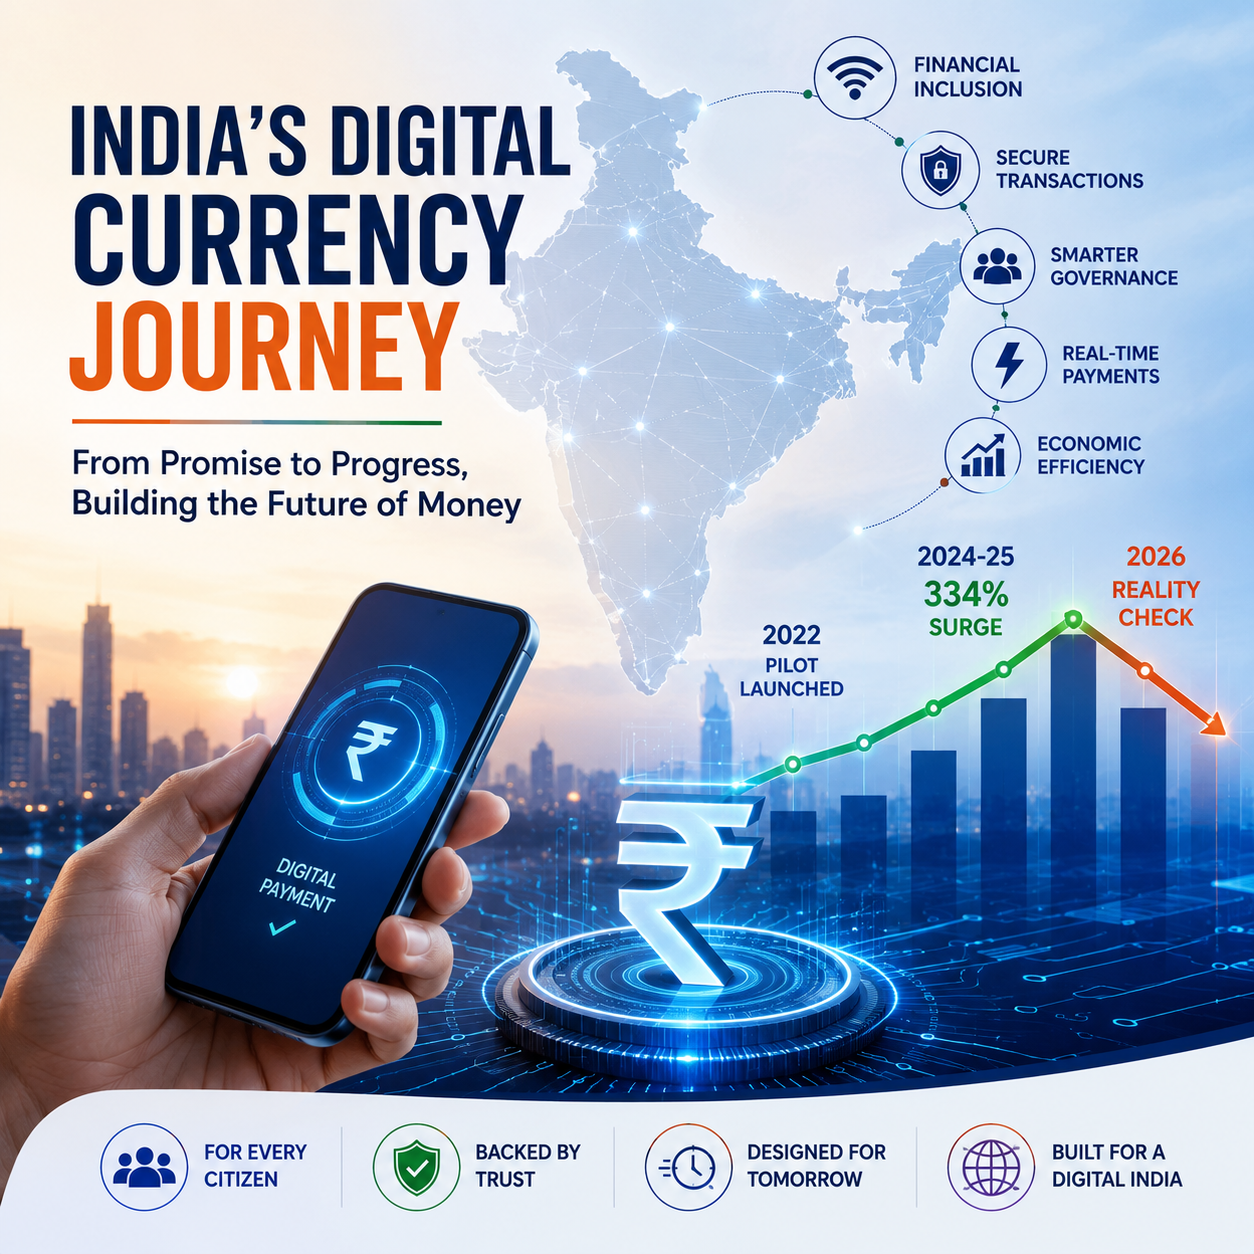
The rupee’s growth story has unfolded in two very different phases. During 2024-25, digital rupee circulation surged 334%, rising from ₹234 crore to ₹1,016 crore as the RBI expanded the pilot to 17 banks and around 60 lakh users. The central bank also began exploring cross-border CBDC initiatives, signalling ambitions that extended beyond domestic payments.
However, the momentum did not continue. According to the RBI’s Annual Report 2025-26, e-Rupee in circulation declined to ₹771.7 crore by March 2026, showing a fall of about 24% from the previous year, though the RBI broadened its experiments into welfare payments, direct benefit transfer programmes, and cross-border transactions.
The contrast is revealing: while the pilot continued to expand institutionally, sustained user adoption proved harder to achieve. The impressive gains of 2024-25 showed what was possible, but the subsequent pullback highlighted how difficult long-term adoption can be.

Benefits of CBDC for the Country
The Digital Rupee promises significant economic advantages across multiple dimensions. It can act as a strong alternative to physical currency. The issuance and circulation of tangible cash requires a long process and high costs.
For instance, for every Rs.100 note, the government spends approximately between Rs.15 and Rs.17. This cost is over a four-year lifecycle on printing, distribution, storage, and replacement due to damage.
Nevertheless, CBDC has the potential to reduce all these costs and hassles. It also eliminates environmental and logistical challenges while providing superior functionality.
Real-time settlement is another great benefit. Unlike traditional banking transactions that can take hours to settle, in the case of the Digital Rupee, it settles instantly. This speed benefits businesses through improved cash flow and reduces counterparty risk significantly.
While these costs are for the government, its true value lies in how this translates into tangible benefits for both payment givers and receivers. Also, an understanding that this system assists in operational improvements, from enhanced security to cross-border transactions.
Tax Efficiency
The Digital Rupee brings unique tax efficiency for both payers and receivers. Unlike cash transactions that leave no audit trail, every Digital Rupee transaction creates an immutable record. This transparency dramatically reduces tax evasion and improves compliance rates across all sectors.
For Taxpayers: The system enables automated tax calculations and deductions. When a business vendor receives any payment through digital mode, GST calculation happens instantly. This allows accurate and automatic tax deduction at source, which reduces human error and compliance costs.
For Government: Real-time transaction visibility means immediate tax collection insights. It automatically flags suspicious transactions, identifies potential tax evaders, and ensures proper GST compliance. This helps to create a more transparent and sustainable economy.
Cost Efficiency
The cost savings from Digital Rupee implementation create measurable improvements in the critical areas, which are:
Security and Fraud Prevention: Counterfeit currency remains a persistent challenge for cash-based economies. Because every e-Rupee is issued and recorded by the RBI, the risk of fake currency entering circulation is largely eliminated. While no digital system is completely immune to fraud or cyber threats, CBDC can significantly reduce the risk of counterfeiting associated with physical banknotes.
Cross-border Facilitation: RBI is expanding the implementation of CBDC for cross-border payments to improve and streamline the hectic and tedious transaction process. The launch of CBDC pilots in select nations is in progress and is on the roadmap for finalization. At the G20, it has been declared that CBDC is an appropriate tool to enhance cross-border payments.

How the RBI Regulates the Digital Rupee
The regulatory framework balances innovation with security and stability. A primary focus is to ensure that the Digital Rupee enhances existing payment systems without disrupting the broader financial ecosystem.
RBI’s Strategic Approach: Throughout the rollout, the RBI has focused on ensuring that the Digital Rupee complements existing payment systems without posing risks to financial stability. Instead of introducing the Digital Rupee nationwide from day one, the RBI has expanded the Digital Rupee in stages to evaluate performance, address challenges, and refine the system along the way.
Policy Integration: The Digital Rupee integrates seamlessly with existing financial regulations. Its transactions receive the same tax treatment as regular currency. This could accelerate the use of the Digital Rupee across industries and sectors.
Risk Management: Financial institutions with reserves in the RBI can only transact in CBDC. It makes it easier to reduce counterparty risks. This creates a more stable and efficient financial ecosystem.
Three Challenges Slowing India’s Cashless Transition
Despite several benefits and significant growth since its implementation, some challenges still need to be addressed. Those are:
Building the right infrastructure:
Reliable internet connectivity is no longer a luxury; it has become an absolute necessity these days, especially in India, which has shown progress in the digital market on global platforms.
One of the biggest challenges that CBDC adoption faces is digital literacy. Although smartphone ownership and internet access have grown significantly across India, many people, particularly older adults, rural communities, and first-time digital users, still struggle to navigate digital financial services.
This matters because a digital rupee can only succeed if people are comfortable using it. Expanding financial inclusion will require not only technology but also digital education and users across the CBDC ecosystem.
Technical complexity to overcome:
The system must handle millions of simultaneous transactions while maintaining security and preventing fraud. Cybersecurity becomes even more critical when an entire currency system operates digitally. One of the most significant challenges for CBDC is to create a system that can support millions of transactions without compromising security, user data, or financial assets.
Ecosystem integration and adoption challenges:
Although India has made considerable progress with UPI, integrating the Digital Rupee into an already successful payments ecosystem remains a challenge. Many merchants and payment aggregators see little reason to adopt a new payment option when UPI already meets most of their needs. Without a clear value proposition, encouraging businesses and consumers to change established payment habits can be difficult.
While interoperability between CBDC and UPI has improved significantly, broader adoption will depend on demonstrating tangible benefits beyond what existing digital payment systems already offer. Users can already make Digital Rupee payments through the existing UPI QR code, reducing friction for merchants and consumers. However, widespread adoption will require more than seamless integration with existing payment systems.
CBDC vs UPI vs Crypto: What’s the Difference?
| Feature | CBDC | UPI | Cryptocurrency |
| Definition | Digital version of government money issued directly by the RBI | A payment interface system that transfers money between existing bank accounts | Decentralized digital assets with value determined by market trading. |
| Backing | RBI guarantee | Bank deposits | Market sentiment |
| Offline capability | Yes, but limited availability | No | No |
| Intermediary | None required | Banks needed | Blockchain network |
As the table shows, the Digital Rupee and UPI serve different functions: one is sovereign digital money issued by the RBI, while the other is the payment infrastructure that enables transactions.
Why Merchant Adoption of e-Rupee Has Slowed
Merchant adoption remains one of the biggest hurdles to the long-term success of the Digital Rupee. While the pilot programme has expanded steadily, merchant usage has not matched the rapid adoption seen during UPI’s growth phase.
Let’s understand how?
Merchant Incentives: Current pilots show limited merchant enthusiasm compared to UPI’s rapid adoption. UPI reduced onboarding friction through zero merchant charges, while the e-Rupee still lacks a clear business incentive for merchants to enable a separate acceptance infrastructure.
Having worked inside banks during the UPI rollout, I saw how fast Indians adopt a payment rail when the incentive is obvious, and the friction is near zero, and how completely they ignore one when it isn’t. That is the real test the e-Rupee has yet to pass.
Customer Demand Remains Low: Merchants typically adopt payment methods that their customers actively use. Since consumer usage of the Digital Rupee is still developing, many businesses see little reason to prioritize acceptance. This creates a network-effect challenge: consumers wait for merchants to accept it, while merchants wait for consumers to use it.
Interoperability Challenges: Seamless integration with existing payment systems remains a work in progress. The system needs to be as simple as UPI while maintaining unique CBDC advantages.
Five Steps India Has Taken Since the 2022 CBDC Launch
● The most significant milestone since the launch of CBDC is when the Reserve Bank of India demonstrated offline digital rupee payments at the Global Fintech Fest 2025 in Mumbai. Using NFC-based and telecom-assisted systems, the RBI showed that wallet-to-wallet e-rupee transfers could happen even without internet connectivity. For users in rural and low-connectivity regions, offline transaction experience can significantly change the practical usefulness of CBDC. It positions the e-Rupee as a potential financial inclusion infrastructure layer.
● Real-world applications of programmable payments include direct benefit transfers to farmers against the generation of carbon credits and loans to tenant farmers under the Kisan Credit Card (KCC) framework. Employee allowances for fuel and meal purposes are also being redirected via the E-Rupee Digital app by banks.
● Odisha has made e-Rupee payments to 88,000 beneficiaries under the Subhadra Yojana. The RBI and government agencies are also exploring additional ways to support welfare payments, subsidies, and other targeted fund transfers through digital rupee.
● To increase adoption and improve distribution, selected non-bank entities have been allowed to offer CBDC wallets. Additionally, the scope of e-Rupee-Wholesale was further expanded and diversified with the addition of four standalone primary dealers (SPDs).
● Comprehensive awareness programs aim to engage with diverse communities and age groups. Digital literacy initiatives focus on practical demonstrations rather than technical explanations. This allows the technology to be accessible to all population segments.

India Is 49% of Global Real-Time Payments. So, Why Is Full Cashless Still 3-5 Years Away?
The digital payment ecosystem of India has demonstrated a remarkable transformation. UPI shows an impressive growth of Rs.23.49 Lakh Crores across 16.58 billion financial transactions in October 2024. It has marked a 45% year-on-year growth from 11.40 billion transactions in October 2023. This represents the country’s appetite for initiating payments through digital mode.
However, cash remains a significant factor in the list of vendors, small businesses, and emergency cases. The Digital Rupee would help fill this gap by providing the cash-like functionality in electronic form, along with the advantages of electronic transactions.
According to the ACI Worldwide Report 2024, India now accounts for around 49% of global real-time payment transactions as of 2023. It highlights India’s leadership in digital payment innovation and positions India uniquely to lead global CBDC adoption.
India’s ambitions for the digital rupee now extend beyond domestic payments. As the holder of the BRICS chair in 2026, India has proposed linking the CBDC systems of BRICS member nations for direct cross-border settlement. The main objective is to enable bilateral trade and tourism payments using respective central bank digital currencies, reducing dependence on traditional dollar-based settlement channels.
The RBI’s roadmap looks slow but determined. Thorough implementation likely depends on pilot success, infrastructure improvements, and user acceptance. And hence, real acceptance may take 3-5 years, provided that existing challenges and public concerns are addressed properly.

Digital Rupee 2026: A Measured Rollout Gaining Momentum
The E-Rupee is more than technological growth. The pilot’s continued expansion and growing functionality are positive indicators of measured progress toward broader implementation.
The primary purpose of bringing this revolution is to offer a digital alternative that combines the best features of cash and electronic payments. Ultimately, success will depend on whether the citizens of India will find the E-Rupee more secure and beneficial than the existing available options.
We are at the early stages of witnessing the world’s largest and most successful digital currency implementation as the pilot expands and infrastructure is enhanced. It is gradual but gaining momentum. The question is how quickly the transition will occur and what ripple effects it will create globally.
What is your view on digital currency adoption? Would you trust keeping your money in the E-Rupee app over the tangible security of cash? Be vigilant, as your answers will help shape not just the financial future of India but also the global monetary evolution.
Explaining a fast-moving, regulation-heavy topic like the digital rupee accurately, in plain language, and with current data is exactly what I do for banks, NBFCs and fintech clients. If that is what your content needs, see my finance writing samples, or get in touch and tell me what you are building.
India’s Digital Rupee (e-Rupee): Frequently Asked Questions
What is the difference between e-Rupee and UPI in India?
UPI is a payment interface that transfers money between bank accounts. e-Rupee is a digital currency issued directly by the RBI, the money itself, not a payment channel. UPI is the road. e-Rupee is the vehicle. You can use UPI to send digital rupees, but they are different layer of India’s digital payment infrastructure.
How many users does India’s digital rupee have?
e-Rupee circulation peaked at ₹1,016 crore (about 60 lakh users across 17 banks) in March 2025, a 334% jump. But the RBI’s Annual Report 2025-26 shows it then fell roughly 24% to ₹771.7 crore by March 2026, even as the RBI expanded pilots into welfare payments and cross-border use. Adoption, by value, has slowed.
Can the digital rupee work without internet in India?
Yes, with limitations. The RBI demonstrated offline digital rupee payments at the Global Fintech Fest 2025 using NFC technology, allowing wallet-to-wallet transfers without internet. This is a significant step for financial inclusion in areas with poor connectivity.
Is India’s digital rupee the same as cryptocurrency?
No. Crypto is decentralized, unregulated, and market-driven in value. The e-Rupee is a legal tender issued and backed by the RBI. It maintains stable purchasing power and is subject to the same regulations as physical currency.
How will India use CBDC for cross-border payments under BRICS 2026?
India holds the BRICS chair in 2026 and has proposed linking the CBDC systems of member nations for cross-border settlements. This would enable direct currency exchanges between national CBDC, reducing dependence on dollar-based settlement and cutting transaction costs for bilateral trade.
References
- https://www.atlanticcouncil.org/cbdctracker/
- https://www.pib.gov.in/PressReleasePage.aspx?PRID=2079544.
- https://www.financialexpress.com/business/digital-transformation-monetary-policy-2024-shaktikanta-das-announces-programmability-and-offline-functionality-for-the-cbdc-retail-pilot-3387769/
- https://www.rbi.org.in/commonman/English/scripts/FAQs.aspx?Id=3686.
- https://www.rbi.org.in/scripts/BS_PressReleaseDisplay.aspx?prid=54773.
- https://www.rbi.org.in/Scripts/PublicationReportDetails.aspx?ID=1218.
- https://www.imf.org/en/Publications/fandd/issues/2022/09/Picture-this-The-ascent-of-CBDCs.
- https://www.ibm.com/think/topics/blockchain-for-cbdc.
- https://www.npci.org.in/what-we-do/upi/product-statistics.
- https://economictimes.indiatimes.com/tech/technology/e-rupee-in-circulation-grows-to-over-rs-1000-crore-rbi-exploring-cross-border-cbdc-pilots/articleshow/121485395.cms
- https://www.moneycontrol.com/news/business/value-of-retail-cbdc-in-circulation-rose-334-in-fy25-rbi-annual-report-13060454.html
- https://www.businessupturn.com/sectors/banking/digital-rupee-in-circulation-falls-24-to-rs-771-7-crore-even-as-rbi-expands-cbdc-pilots/
- https://economictimes.indiatimes.com/news/economy/finance/digital-rupee-to-save-costs-of-printing-distributing-and-storing-cash/articleshow/89413532.cms?from=mdr
- https://www.ibef.org/news/rbi-s-offline-digital-rupee-is-here-pay-with-e-even-without-internet
- https://www.reuters.com/world/india/indias-central-bank-proposes-linking-brics-digital-currencies-sources-say-2026-01-19/
- https://www.rbi.org.in/commonperson/english/scripts/Notification.aspx?Id=2620
- https://www.aciworldwide.com/real-time/india
- https://www.npci.org.in/purpose-value
- https://www.rbi.org.in/Scripts/PublicationReportDetails.aspx?UrlPage=&ID=1218
Originally published: February 2026 | Last updated: June 2026 | This article is for informational purposes only and does not constitute financial or investment advice.

Written by Sundhara, a finance and business content writer with 9+ years in banking. As a Credit Officer at Bank of Baroda she assessed corporate and retail credit risk, and as a Wealth Relationship Manager at ICICI Bank she managed HNI and UHNI portfolios. With an MBA in Finance, she writes research-backed, compliance-aware content across finance and fintech, business and brand. Her work pairs real industry experience with editorial precision.
Leave a Reply